Anthropic Files IPO with $518B Infrastructure Bet
Market eyes $2T valuation — but can revenue growth outpace astronomical compute costs?
On September 28, Reuters obtained key financial disclosures from Anthropic’s confidential IPO filing — revealing an unprecedented commitment: $51.8 billion in annualized compute and infrastructure spending, culminating in a staggering $518 billion of long-term contractual obligations over the coming years.
This aggressive capital deployment underpins a projected IPO valuation exceeding $2 trillion, positioning Anthropic among the most valuable private tech companies globally — rivaling SpaceX’s $1.77T public debut in June 2026.
📈 Explosive Growth — and Eye-Watering Losses
| Metric | 2024 | 2025 | YoY Change |
|---|---|---|---|
| Revenue | ~$400M | $4.6B | +1,050% |
| Operating Loss | — | $8.06B | — |
| Net Loss (GAAP) | — | $42.0B | — |
While revenue surged nearly 12× year-over-year, the $42B net loss includes $34B in non-cash accounting charges tied to revaluation of convertible financing instruments — not cash outflow. Still, the underlying operational reality is stark:
- $7.33B spent on compute & infrastructure in 2025 alone — ~58% of total operating expenses.
- Claude Code’s weekly active users doubled since January 2026 — signaling rising demand — and rising cost pressure.
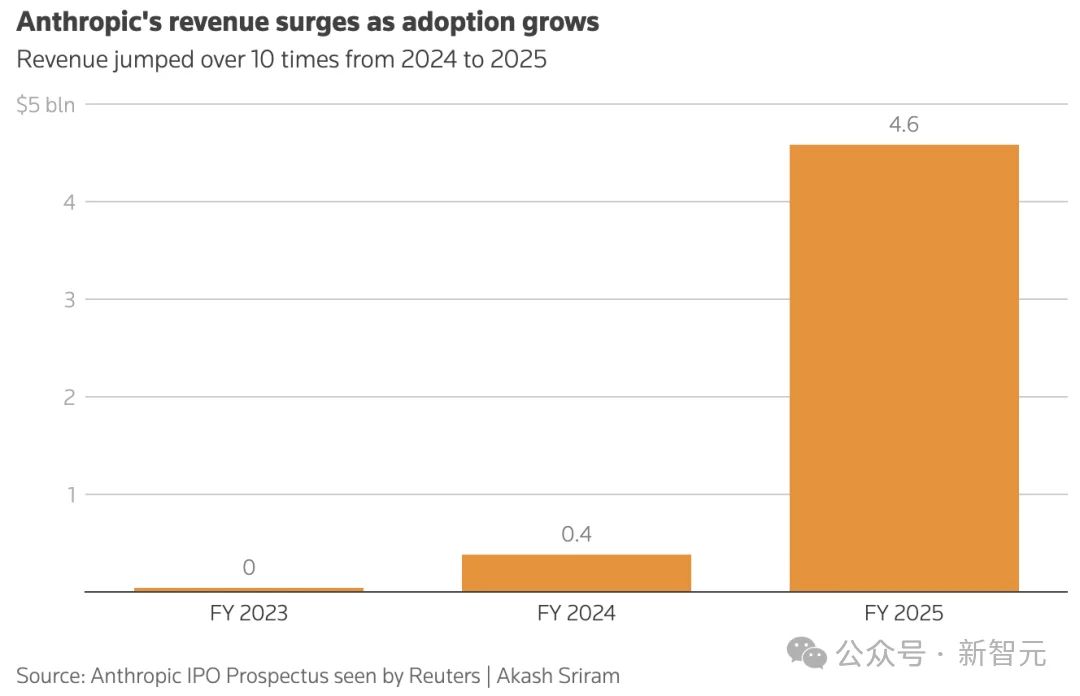
Anthropic revenue jumped from ~$400M in 2024 to nearly $4.6B in 2025. (Source: Reuters)
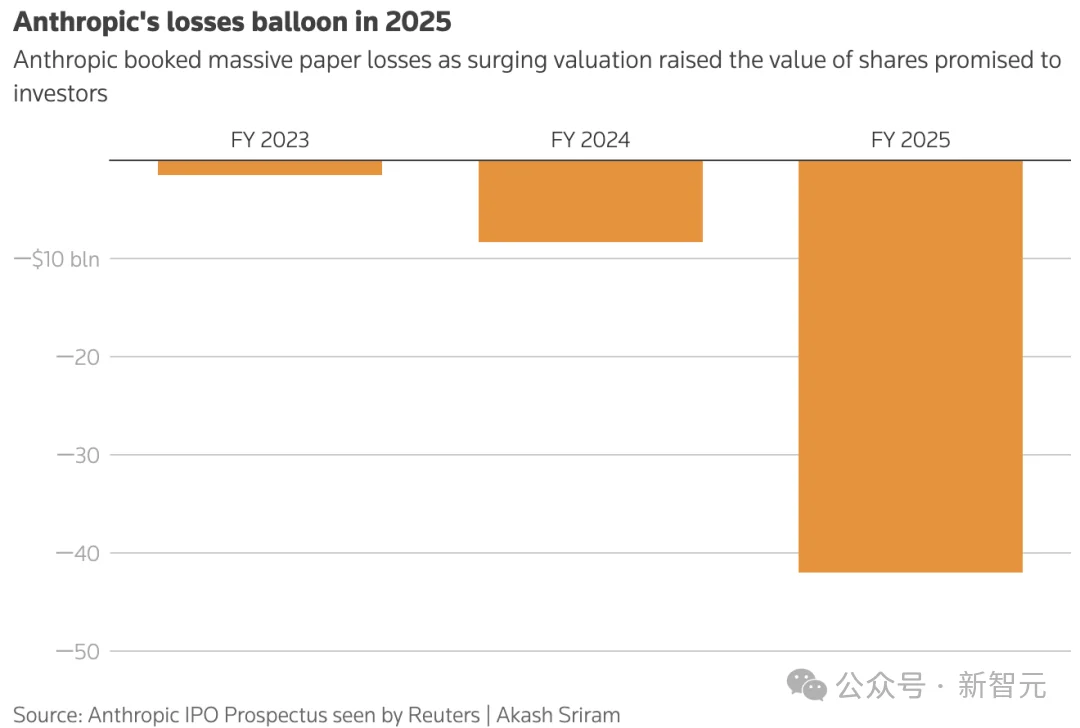
$42B net loss driven largely by $34B in financing-related accounting adjustments. (Source: Reuters)
⚙️ The $518B Compute Commitment
Anthropic has locked in massive future capacity through strategic partnerships:
- ✅ Amazon Web Services — Expanded cloud infrastructure agreement
- ✅ Google Cloud — Dedicated AI accelerator access
- ✅ Broadcom — Custom silicon and networking infrastructure
- ✅ SpaceX — GPU compute collaboration (unprecedented for an LLM firm)
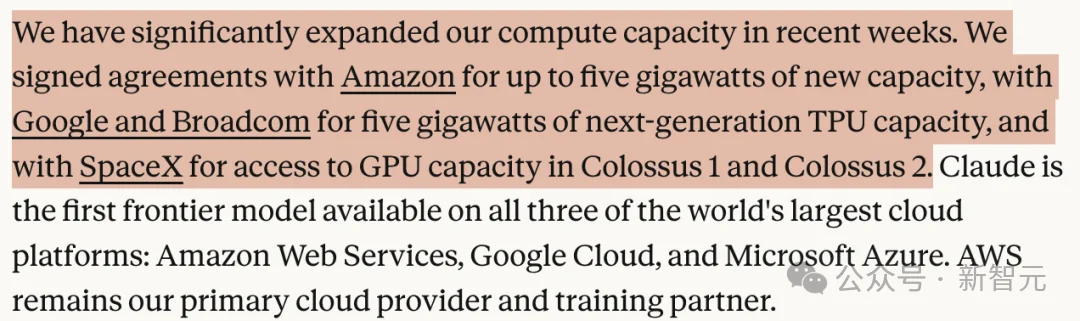
Anthropic’s multi-billion-dollar agreements with AWS, Google, Broadcom, and SpaceX. (Source: Reuters)
But infrastructure pre-commitments carry risk: Demand isn’t guaranteed. With no long-term contracts binding many top customers, revenue stability remains fragile.
⚠️ Concentration Risk & Contractual Uncertainty
- ~24% of 2025 revenue came from just two unnamed enterprise clients.
- Multiple major customers operate on short-term or month-to-month agreements — exposing Anthropic to sudden budget cuts or competitive switching.
- As noted in its risk factors: “Certain large customers may reduce or discontinue their spending at any time.”
This concentration amplifies volatility — especially as Anthropic scales compute spend ahead of confirmed usage.
🎯 Valuation Anchored in 2028 Projections
Investors aren’t pricing today — they’re betting on tomorrow:
- Projected 2028 revenue: $190B–$200B (per Reuters’ August report)
- $47B annualized run rate achieved in May 2026, post-$65B Series F round (post-money valuation: $965B)
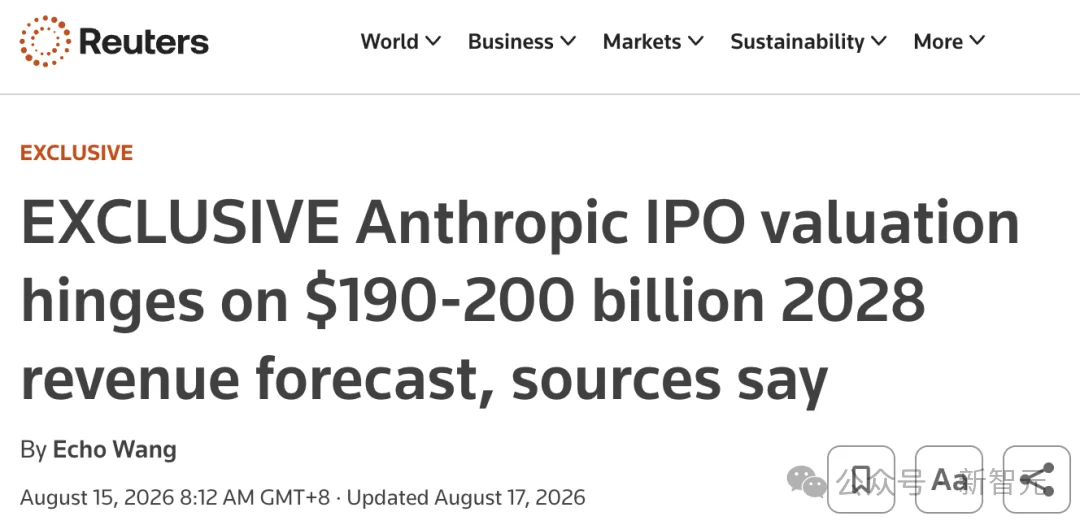
Forward-looking revenue targets driving investor expectations. (Source: Reuters)
Yet this hinges on three critical conditions:
1. Sustained enterprise adoption across coding, RAG, and agentic workflows
2. Claude’s continued technical differentiation vs. OpenAI, xAI, and open-weight models
3. Gross margin expansion, as revenue growth outpaces compute cost inflation
🔮 What Comes Next?
- IPO timing likely delayed until after the November 2026 U.S. midterm elections.
- OpenAI has also filed confidentially, with potential listing expected in early 2027.
- Ultimately, market confidence won’t rest on vision — but on recurring, scalable, profitable usage.
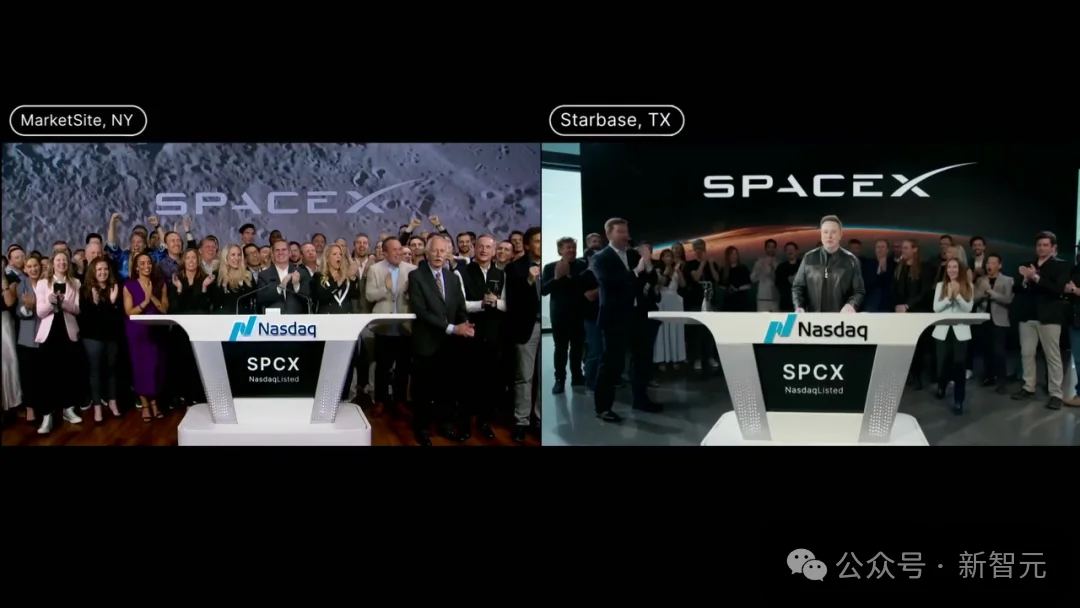
SpaceX’s $1.77T IPO sets a high bar — but Anthropic must prove its path to profitability is equally tangible. (Source: Reuters)
💡 Bottom line: Capital markets are pricing Anthropic like a utility — but it’s still a startup racing to convert hype into habitual, high-margin usage. Every dollar of subscription revenue must now justify millions in committed infrastructure spend.
Sources: Reuters — Anthropic’s IPO Prospectus
Published: September 29, 2026 | Coverage by AITNT — Global AI Intelligence Platform